Internal Water Damage
Water escaping from inside your home:
- Burst or frozen pipe
- Failed appliance line
- Water heater leak
These sudden events are the kind homeowners policies may address, depending on the policy and the cause.
A homeowner's guide for Durango and Southwest Colorado
The first 48 hours decide how big this problem gets. Here's your plan.
If there's water in your home right now, take a breath. You're about to have a plan.
Water damage doesn't give you time to research. It keeps moving into flooring, drywall, and framing while you're still deciding who to call. That's why the first day or two matter so much. Not because of some magic deadline, but because everything gets simpler when you act early: the cleanup, the drying, the documentation, and yes, the insurance side too.
The problem is that nobody teaches you this ahead of time. So the moment it happens, you're dealing with an emergency and being asked to make important decisions at the same time. Nobody is at their best under those conditions.
Here's the good news. You don't have to figure this out alone. This guide walks you through exactly what to do first, what to document, where insurance fits in, and the mistakes that cost Durango homeowners the most.
Start with the checklist below. Everything after it explains the why.
Each of these steps is explained below.
Water doesn't wait for your claim to be processed. It keeps moving into flooring, drywall, and framing whether the loss ends up covered or not. It follows gravity and finds the path of least resistance, which usually means it travels into places you can't easily check.
The longer moisture sits in building materials, the harder it becomes to know the full extent of what's affected, and moisture that lingers in enclosed spaces creates the conditions mold needs.
So regardless of what your coverage turns out to be, the water emergency itself needs to be taken seriously right away. While the coverage question gets sorted out, your job is to document what's happening and get the damage properly evaluated.
Before anything else, check for danger. Standing water near outlets or electrical panels, a sagging ceiling, or any doubt about the structure means you stay out. If you're not sure the space is safe, leave and get the proper emergency help first.
If the area is safe, shut off the supply. That may mean the main water valve, or the shutoff behind an appliance or under a sink. If the water is coming from outside, from a storm or rising water, the source may be out of your hands, and your focus stays on safety.
Photos and video before anything gets moved, cleaned, or thrown away. Wide shots for context, close-ups for detail. Start a simple timeline in your phone: when you found it, what you think caused it, what you did and when.
Towels and a shop vac are reasonable tools for the water you can see. Keep wet materials away from dry areas, and don't wait for an odor to tell you it's urgent.
Airflow helps: move furniture off wet flooring, get air circulating where conditions allow. Just know that household fans dry surfaces, and surfaces are not the whole story.
Water travels under flooring, behind baseboards, into wall cavities, insulation, and subfloor. A musty smell or dampness that keeps coming back means moisture is still present somewhere you can't see it.
If water spread into walls, floors, or multiple rooms, or you're simply not sure how far it went, a professional assessment tells you what you're actually dealing with. If the damage is minor, you'll know that too.
Not every water loss is the same. A pipe leak, a roof leak, and floodwater call for different first moves, and the source of the water matters for cleanup, safety, and insurance.
Immediate actionShut off the water source if safe and document the affected areas.
Worth checkingWalls and flooring near the leak often hold moisture you can't see.
Immediate actionStop the water source if possible and check surrounding flooring and walls.
Worth checkingTanks release a lot of water fast. Look beyond the closet it sits in.
Immediate actionStop the appliance and its supply line, then remove standing water.
Worth checkingNearby cabinets, flooring, and subfloor can absorb water quietly.
Immediate actionProtect the area below if safe and address the source of the intrusion.
Worth checkingA ceiling stain can point to a larger problem above it.
Immediate actionPrioritize safety and avoid contact with potentially contaminated water.
Worth checkingFlooding is treated differently by insurance. See the flood section below.
Immediate actionLimit exposure. Contaminated water is not a clean-water leak and needs stricter caution.
Worth checkingBackup coverage is commonly an optional add-on. Check your policy.
Here's the whole plan compressed into one view. This is a practical rhythm, not a legal deadline or an insurance rule. Nothing terrible happens at hour 49. The point is simply that moisture gets harder to understand the longer it sits.
Safety first, stop the source if you can, and document everything before it gets moved or cleaned.
Remove standing water, get the affected area assessed, and begin proper drying.
Monitor moisture levels over time, address affected materials, and keep records of the restoration work as it happens.
This is the part most homeowners have never been told, and it's where a lot of expensive surprises come from.
When water shows up in a home, the natural response is to attack it with whatever is on hand: towels, a shop vac, a couple of box fans. And to be fair, that effort often works on the water you can see. The floor gets dry to the touch. The carpet stops squishing. It looks handled.
The problem is that "looks dry" and "is dry" are two different things.
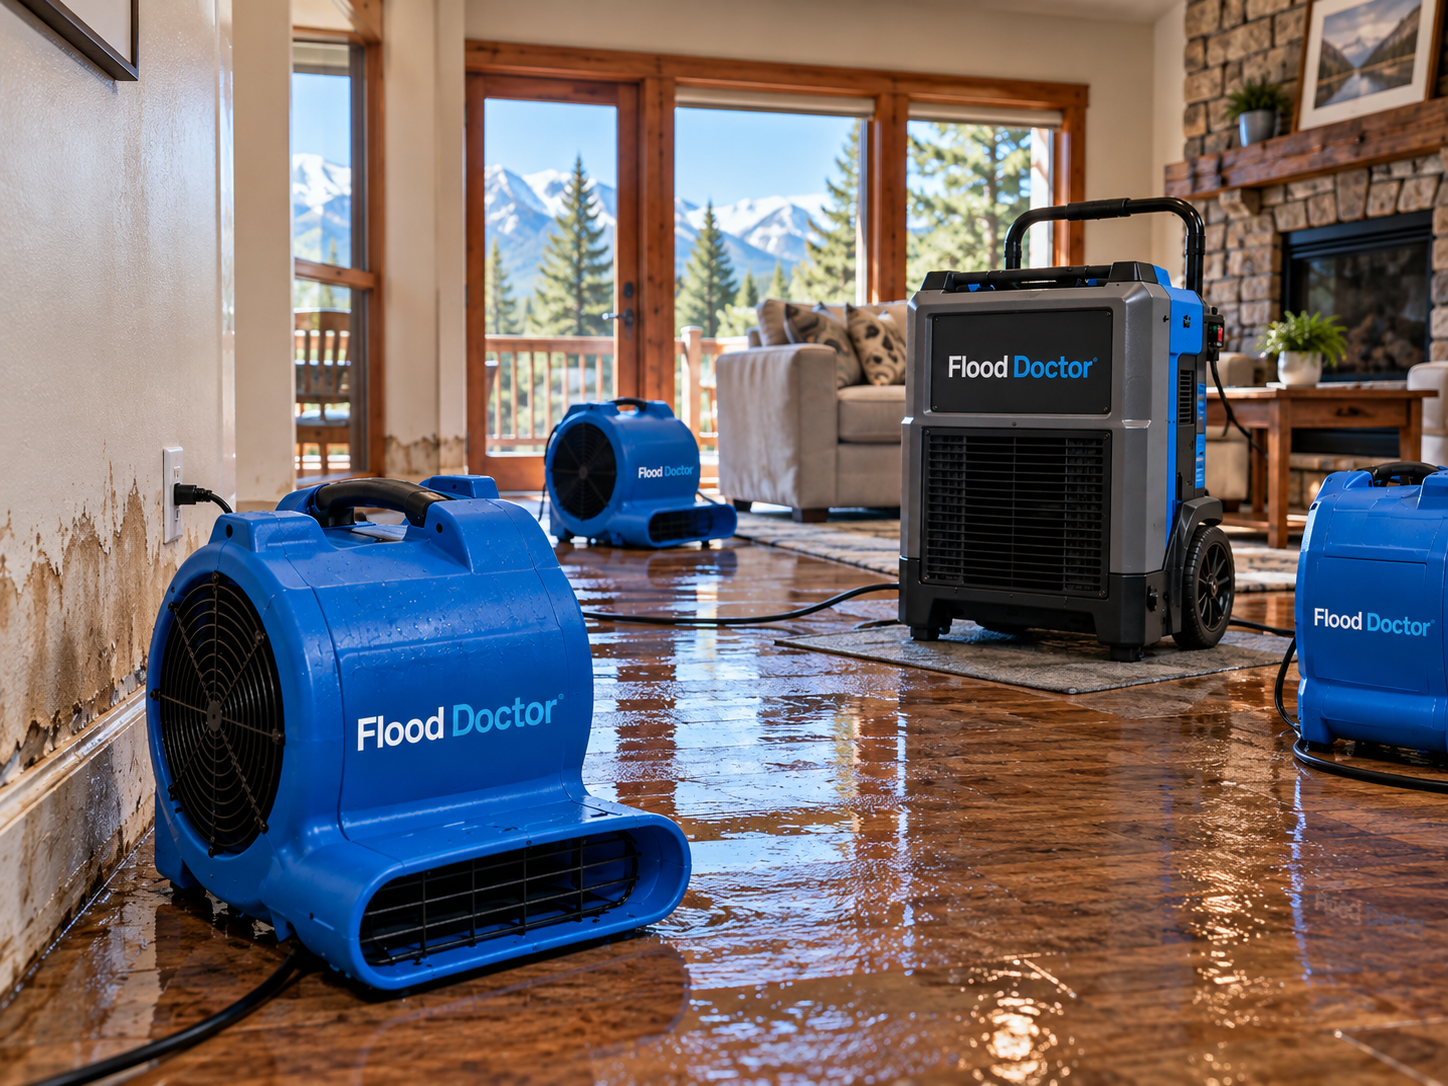
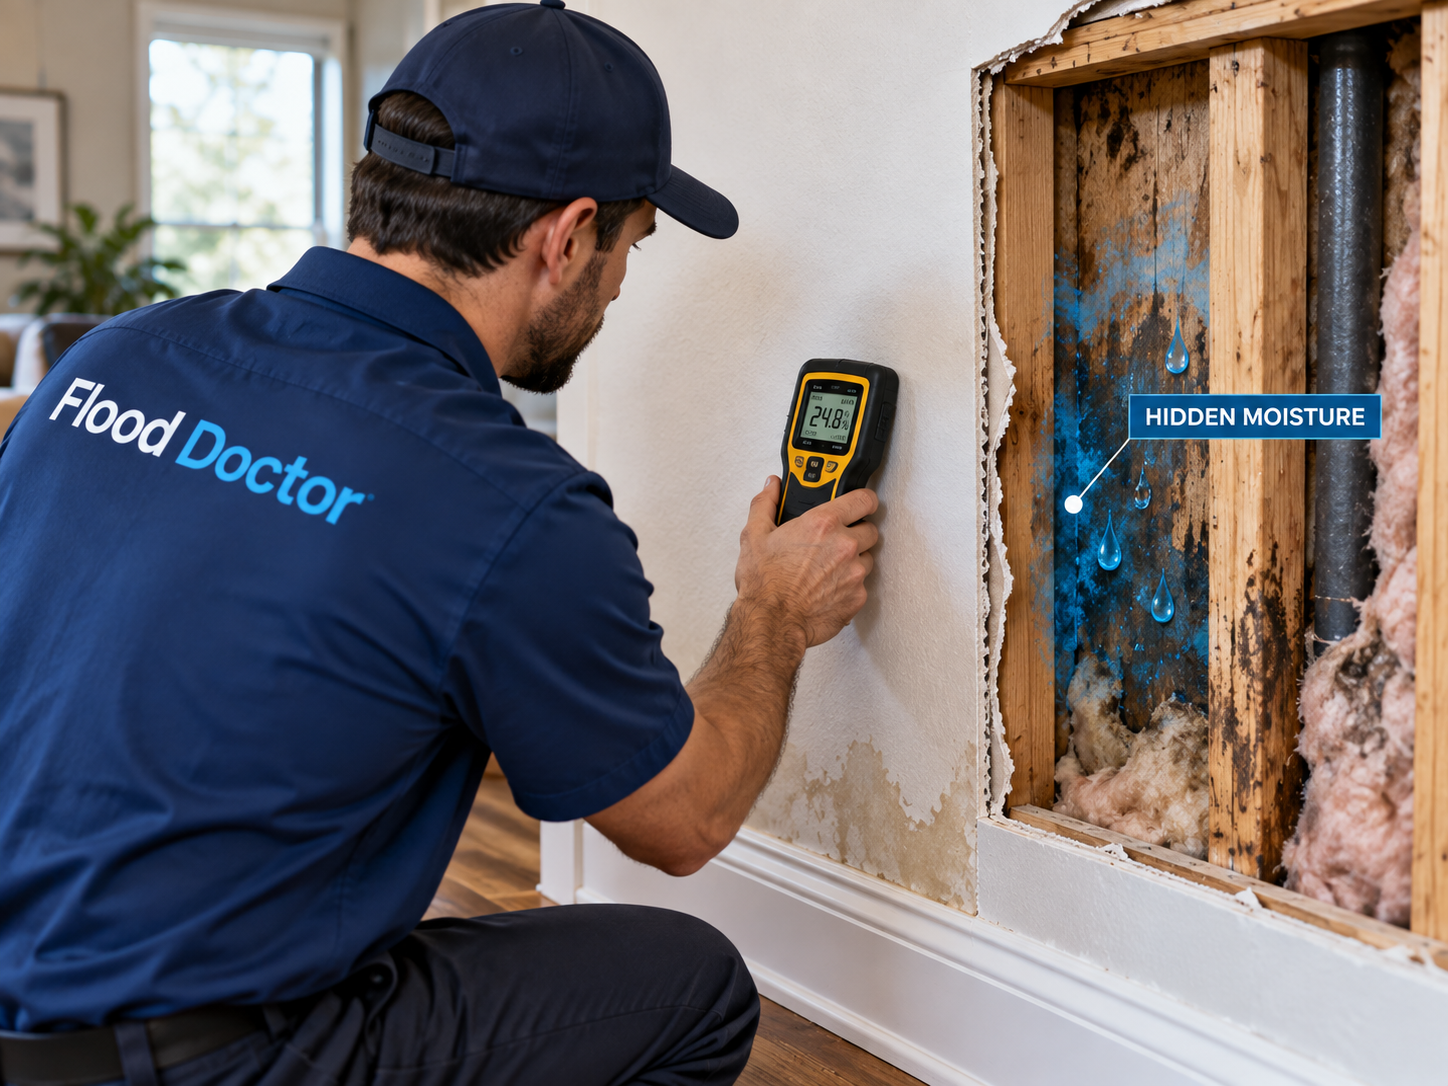
That's why professional restoration doesn't rely on eyes and hands alone. A proper evaluation of water damage generally involves:
None of this is meant to make you feel bad about grabbing the shop vac. Removing visible water quickly is a reasonable thing to do. The point is simpler than that:
A surface can look dry while moisture is still present where you can't see it. That's exactly the situation a professional evaluation exists to catch.
There's a practical documentation angle here too. A prompt professional assessment helps establish the actual extent and condition of the affected materials while the situation is fresh, and it starts a documented record of the damage and the restoration process from day one, rather than leaving you to piece the story together later.
That's a legitimate reason to have it professionally assessed before you assume anything.
Get Your Free Water Damage AssessmentMost homeowners instinctively grab towels before they grab their phone. That's understandable. But if a claim is filed later, the record of what happened can matter a great deal, and many homeowners simply don't know what information will actually be useful.
Documentation requirements vary by insurer and policy. The goal isn't a universal checklist. It's making sure that whatever your insurance company ends up needing, you actually have it.
A few practical notes on how to do this well:
Photograph before you move anything. Standing water, wet flooring, stained ceilings, soaked drywall, the source if you can identify it. If something has to be discarded for safety reasons, photograph it first. More is better than less.
Keep the timeline simple. When you discovered the damage, what you believe caused it, what you did and when, who you called, when they responded, what was said. Notes on your phone are fine. A clear timeline is much easier to build in the moment than to reconstruct from memory two weeks later.
Keep everything from restoration work. Estimates, moisture readings, drying logs, invoices, before-and-after documentation. Professional restoration records create a much more complete picture of what happened to your home than photos alone.
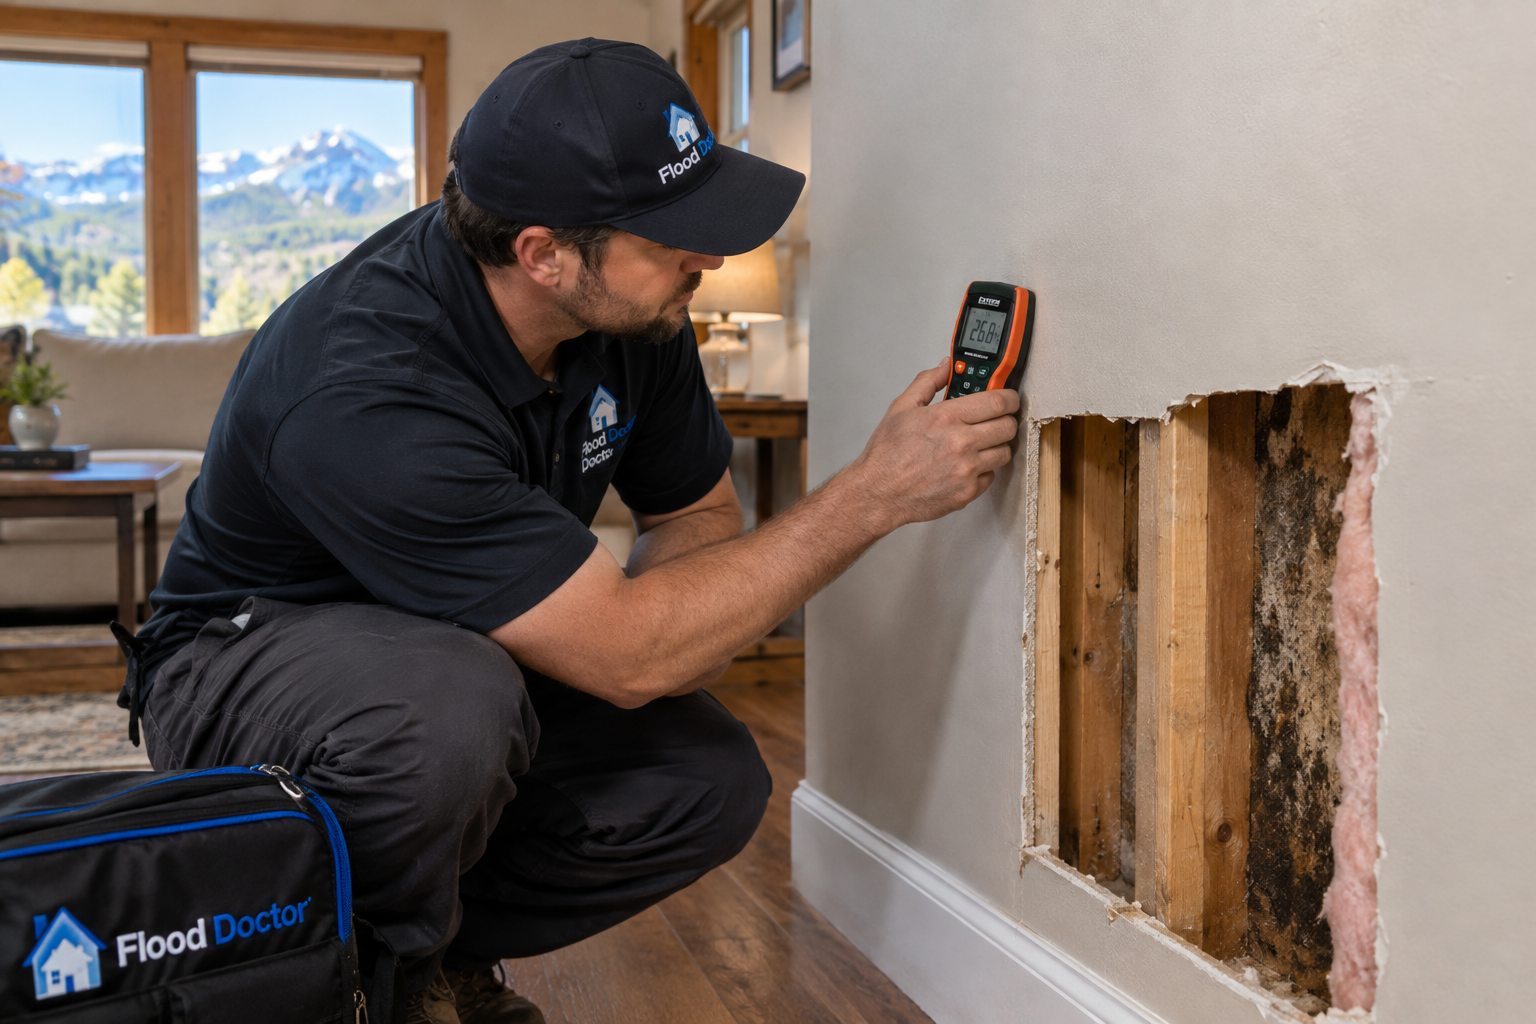
With the physical response underway, the money question moves to the front. And the honest answer is: it depends.
Anyone who gives you a flat yes or no without reading your policy is guessing. Homeowners policies pay for damage caused by the perils listed in the contract, and every policy defines those perils, exclusions, and endorsements a little differently. Whether water damage is covered typically comes down to a few things:
This is why the first practical step isn't guessing. It's contacting your insurance company, reviewing your policy, and asking direct questions about your specific situation. Your insurer determines coverage under your policy. We'll cover exactly what to ask a little further down.
This distinction confuses a lot of homeowners, and it matters more than almost anything else in this guide.
In everyday conversation, "my basement flooded" can mean a water heater let go, a pipe froze and split, or the Animas jumped its banks. To your insurance, those are very different events.
Water escaping from inside your home:
These sudden events are the kind homeowners policies may address, depending on the policy and the cause.
Water entering from outside. FEMA and the National Flood Insurance Program define a flood, in general terms, as an excess of water on land that is normally dry: overflowing rivers or streams, unusually rapid runoff, or mudflows.
Most standard homeowners policies do not cover flood damage. Flood insurance is generally a separate policy.
That's not a fine-print technicality. It's the basic structure of how these two types of insurance work in the United States.
The City of Durango participates in the National Flood Insurance Program, which is what makes federally backed flood insurance available to property owners here, and FEMA flood maps identify flood hazard areas in and around the city. Durango has an established floodplain management program, which tells you something simple: flooding is a recognized local issue, not a hypothetical one.
Two things are worth knowing about flood risk in our area:
First, flood risk is not limited to the mapped high-risk areas. According to FEMA, roughly one-third of NFIP flood claims over the past decade came from outside high-risk flood zones. Spring snowmelt, heavy rain, and rapid runoff, including runoff from land burned by wildfire, can all cause flooding, and those are all familiar conditions in Southwest Colorado.
Second, being outside a high-risk zone doesn't mean you have no risk, and being inside one doesn't automatically mean you're uninsured. Some mortgage agreements require flood insurance for properties in high-risk areas. The practical move is to check your actual situation: look up your property on FEMA's flood maps, and ask your insurance agent whether you have flood coverage and whether it makes sense for your property.
This is not to say every Durango homeowner needs flood insurance. It's to say that every Durango homeowner should know their flood risk and know what their policies do and don't cover, before water is involved. If you decide you want flood coverage, know that a new NFIP policy typically has a waiting period before it takes effect, so it isn't something you can add mid-emergency.
Sewer and drain backup sits in its own category, and the coverage rules depend on both the cause and the policy.
On the homeowners side, sewer or water backup coverage is commonly an optional add-on. Some policies include it through an endorsement; many don't include it by default. The only way to know is to check your specific policy or ask your agent directly.
On the flood insurance side, the NFIP draws the line at cause: a sewer backup may be covered when it's directly caused by flooding, such as during a heavy rainstorm, but not when the backup happens for another reason, like clogged pipes.
So the honest answer on sewer backup is the same as everything else here: coverage depends on the cause and the policy. If you don't know whether you have backup coverage, that's a question worth asking your insurer this week, not during an emergency.
These come up again and again, and every one of them is made by smart, responsible people trying to do the right thing under stress.
Waiting doesn't make water damage smaller. It just makes it harder to understand. If the damage turns out to be minor, an assessment will tell you that. If it isn't, you'll be glad you found out early.
Towels and shop vacs remove visible water. What they can't do is tell you whether the wall cavity is wet or the subfloor absorbed water. The gap is in tools and information, not effort.
The company you choose will be producing much of the record of what happened to your home. That's worth choosing deliberately, even under pressure.
A handful of pictures of a wet floor isn't the same as a complete record of the damage, the cause, the timeline, and the restoration work performed.
Water damage drops you into a world with its own vocabulary and rules. You don't get points for figuring it out solo, and professional support can take a real portion of that mental load off your plate.
A note on choosing a restoration company, since that decision usually happens fast: before you hand someone your home and a role in documenting your loss, it's worth a few minutes to check whether they communicate clearly, have real experience with residential water damage, document their work thoroughly, can handle the full restoration rather than only part of it, and understand how the claims process works from the homeowner's side.
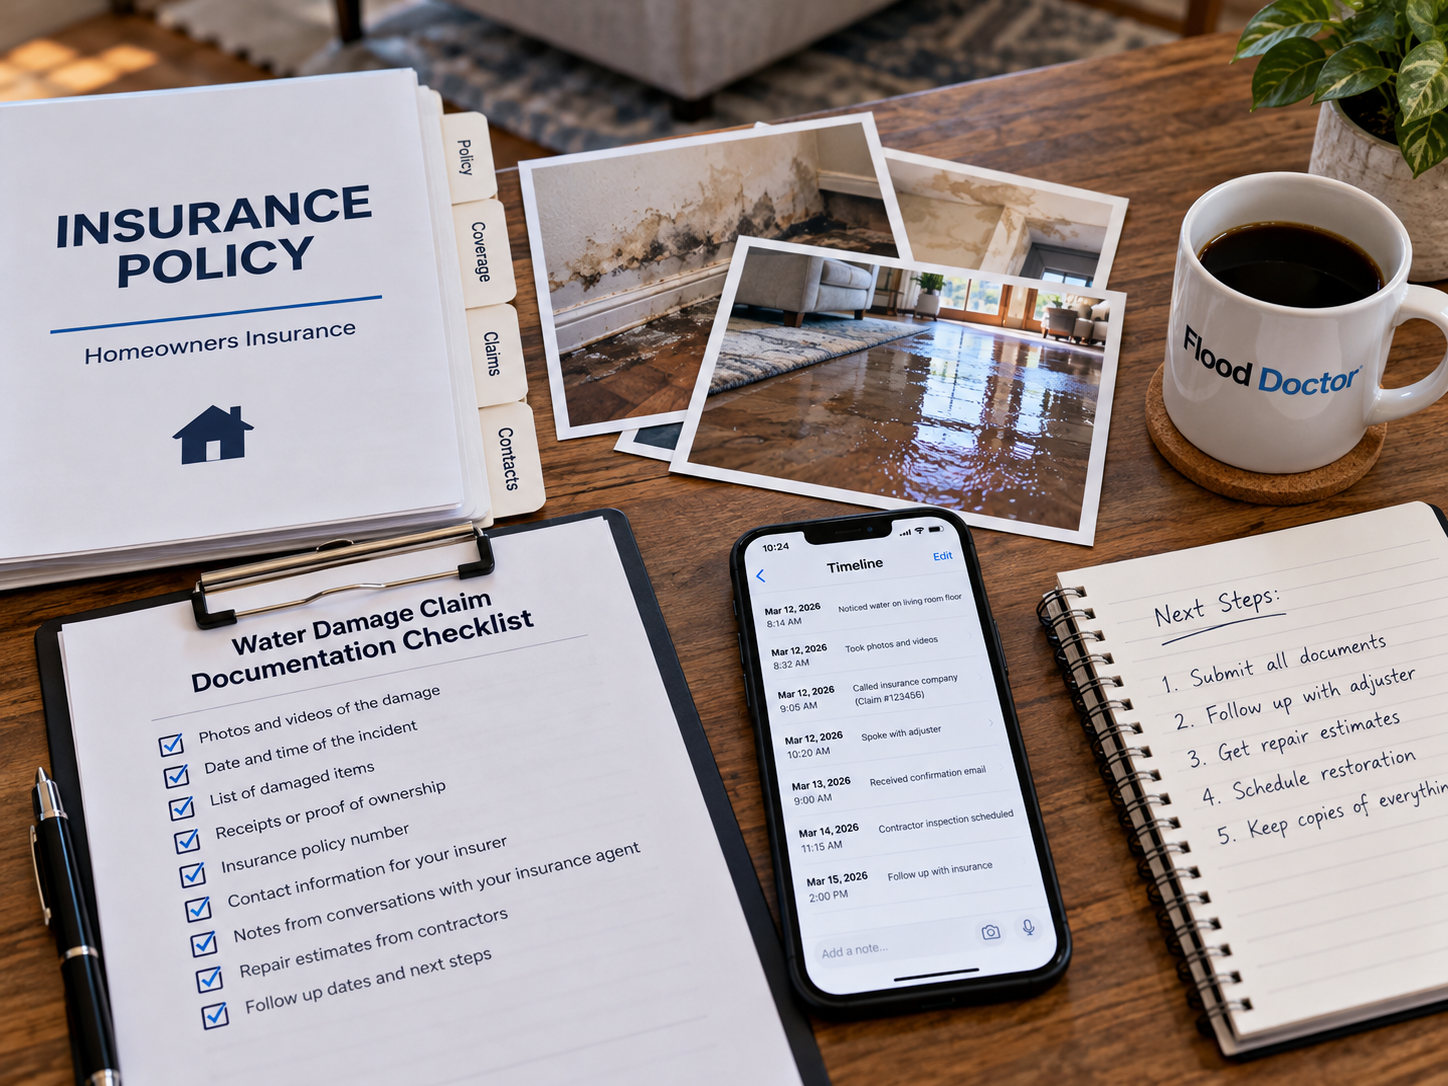
It helps to understand that after water damage, you're dealing with two separate tracks that run at the same time, connected by a third: documentation.
Determines what your policy may cover. That decision belongs to your insurance company, applying your policy to the circumstances of the loss.
Addresses the physical water damage: extraction, structural drying, moisture detection, cleaning, and restoring your home to normal.
Creates the record of the damage and the work performed: estimates, moisture readings, drying logs, and photos.
No restoration company decides what your insurer will pay, and you should be cautious of anyone who suggests otherwise. Where the two tracks meet is documentation and communication. Restoration professionals who work with the claims process regularly can communicate with adjusters about the work being performed and help homeowners keep the process organized. What they cannot do, and what no one can honestly promise, is control the coverage decision. That stays with your insurer.
Your insurance company decides what your policy pays for. A good restoration company makes sure the physical problem is actually solved, and that the record of what happened to your home is thorough and complete.
When you call your insurer, having a short list of direct questions turns a stressful call into a productive one. Start here:
Write the answers down, along with the date, the time, and the name of the person you spoke with. Add it to that timeline you started earlier.
To be clear: asking good questions doesn't guarantee coverage. Your insurance company determines coverage under your policy. What good questions do is remove guesswork. You'll know what your policy says, what your insurer expects from you, and what happens next. That alone eliminates a large share of the stress in this process.
A professional restoration process for residential water damage generally involves some combination of:
If you ask a homeowner in the middle of a water emergency what they want, they'll say "get the water out." But that's the surface answer.
What they actually want is their home back. The one where the floor is just a floor, the family feels safe, and nobody is thinking about what might still be wet behind the drywall. They want their normal routine back. They want to know, not hope, that the problem was handled correctly. And they want one less thing to carry.
That's the real shift good restoration provides. Not just from wet to dry, but from panic to calm. From feeling helpless to feeling in control. From second-guessing every decision to knowing what happens next and why.
This is why professional help is worth more than the equipment it shows up with. The equipment dries your house. The process, the documentation, the communication, and the plan are what bring structure to a week that would otherwise run on adrenaline and guesswork.
If you take nothing else from this guide, take this:
Water damage is a solvable problem. Homeowners get through it every day. The ones who come out with the least stress and the fewest surprises are the ones who documented well, asked good questions, and got a clear picture of the damage early instead of guessing.
Water damage is stressful enough without trying to figure out everything yourself. A professional assessment can help you understand exactly what you're dealing with, what may be hiding beyond what you can see, and what steps may need to happen next. That clarity is the difference between guessing and knowing.
GET YOUR FREE ASSESSMENTServing Durango & Southwest Colorado
Make sure the area is safe, stop the water source if you can do so safely, and document the damage with photos and video before moving or discarding anything. Then begin safe removal of visible water and have the affected area assessed.
It depends on the cause of the damage, your specific policy, and the circumstances of the incident. Your insurance company determines coverage under your policy, so the practical step is contacting your insurer, reviewing your policy, and asking direct questions about your situation.
Most standard homeowners policies do not cover flood damage. Flood insurance is generally a separate policy, often through the National Flood Insurance Program. Check your property on FEMA's flood maps and ask your agent whether you have flood coverage. A new NFIP policy typically has a waiting period before it takes effect.
Sewer or water backup coverage is commonly an optional add-on to homeowners policies, and many policies don't include it by default. On the flood insurance side, the NFIP may cover a backup directly caused by flooding but not one caused by something else, like clogged pipes. Check your specific policy or ask your agent.
Drying should begin as soon as the area is safe. Moisture that lingers in building materials creates the conditions mold needs, and proper drying is confirmed with moisture readings taken over time, not by how surfaces feel to the touch.
Yes. Water travels under flooring, behind baseboards, into wall cavities, insulation, and subfloor. A surface can feel completely dry while the materials underneath are still holding moisture, which is why professionals use moisture meters and thermal imaging.
Yes. Take photos and video of the affected areas, damaged belongings, and the water source before anything is moved or thrown away, and keep a simple timeline of what happened and what you did. If something must be discarded for safety, photograph it first.
When water has spread into walls, floors, or multiple rooms, when contamination may be involved, or any time you're unsure how far the damage goes. If the damage turns out to be minor, a professional assessment will tell you that too.
The first 48 hours, step by step: safety, documentation, drying, hidden moisture, and where insurance fits in.